Mortgage Brokers Continue Fight for Competition
Katherine Martin • March 23, 2017

As you may well be aware, the government has recently made changes to the way mortgages are qualified through the Canadian Mortgage and Housing Corporation (CMHC). In short, these changes have made it more expensive for some of the broker channel lenders to fund mortgages, the increased cost of doing business is then passed on to consumers through higher interest rates. This government intervention has led to an unfair playing field, which means when you consider all your mortgage options, you now have less options than you did before. As an industry, we don’t believe this is right, and we’ve taken our concerns to Ottawa. 

Here is an article titled  Mortgage Industry Voices Concerns to Ottawa  that was published on Canadian Mortgage Trends, a publication of Mortgage Professionals Canada. It provides a highlight of what mortgage brokers are doing to continue the fight for better mortgage products for Canadians. 

Mortgage Industry Voices Concerns to Ottawa

A delegation of mortgage industry leaders went to Ottawa this month. Its mission: to educate lawmakers about the implications of the latest mortgage regulations.

The event, organized by Mortgage Professionals Canada, was its first-ever Parliament Hill Advocacy Days. In just over two days, the group participated in more than 30 meetings involving more than 100 members of parliament, senators and senior policy staff.

The association’s core message centred on the economic ramifications of the new policies that came into effect last fall and January.

Face-to-Face Progress

“Many of the MPs could describe stories from their own riding of homebuyers who were affected by these changes,” said Paul Taylor, President of Mortgage Professionals Canada. “Others were less familiar with our issues but were appreciative of us bringing them to their attention. In all cases, we were delivering messaging to support the channel, to support choice and accessibility for the Canadian consumers we all serve day to day…”

Among those who participated in the effort were familiar industry names like Boris Bozic (Merix Financial), Eddy Cocciollo (Mortgage Centre), Jared Dreyer (VERICO Dreyer Group Mortgage Brokers), Claude Girard (Laurentian Bank), Dan Putnam (CLMS), Amanda Roy-Macfarlane (AMBA), Hali Strandlund (Fisgard Asset Management), Michael Wolfe (AMBA) and Dustan Woodhouse (DLC), among others.

The group conveyed to parliamentarians the recommendations that Mortgage Professionals Canada has publicly put forward, including asking the government for a moratorium on further rule changes for the next 12-18 months, as well as revisiting its anti-competitive position on refinancing.

Boris Bozic, CEO of Merix, said one of the key concerns was the new stress test rules and the need for any changes to be applied to all mortgage types (not just insured mortgages), and all financial institutions. “If the government is truly concerned about debt levels being incurred by Canadian homeowners, the stress test should be applied equally,” he said. “This would ensure that Canadian homeowners continue to have choice, and allow Canadian borrowers to benefit from competition.”

Overall, the group was pleased with how their position was received by members of parliament and other government officials.

“Our concerns were heard and appreciated by all the MPs we met with, irrespective of party affiliation,” Bozic said. “They all committed to raising the issue with their colleagues and sharing our recommendations for slight modifications to the new rules imposed on our industry and middle-class Canadians. Time will tell if the Department of Finance will be receptive to the modifications we suggested.”

Dunning Takes on the DoF

Mortgage Professionals Canada’s chief economist Will Dunning also made a submission to the Standing Committee on Finance in which he presented his analysis of the flaws with the government’s changes and the risks they pose.

“The policies announced on October 3 will reduce housing activity and weaken the broader economy,” Dunning said. “Even in the very best of economic times, a policy that will weaken the economy should be undertaken only after thorough discussion.”

He noted that the Trump presidency raises economic risks for Canada, which he argues justifies rescinding the government’s changes to mortgage insurance. Here’s Dunning’s analysis.

The Next Steps

In an update posted on its website, Mortgage Professionals Canada outlined the expected timeline for the Standing Committee on Finance to finalize its report and recommendations for the Minister based on the testimonies it heard concerning the mortgage changes.

The report isn’t expected to be tabled and made public until at least July or August. In the meantime, the association says the industry “needs to remain active in educating MPs, officials, and the Minister of Finance on how these changes will increase interest burdens, obstruct competition and harm local economies across Canada.”

The mortgage industry has another shot at having its voice heard this Wednesday when DLC President Gary Mauris and our own Editor Robert McLister meet with Deputy Bank of Canada Governor Larry Schembri. The Bank of Canada routinely consults with the Department of Finance on housing issues and Schembri aims to better understand our industry’s perspectives on its policy changes. We’ll keep you posted on that meeting.
Katherine Martin


Origin Mortgages

Phone: 1-604-454-0843
Email: 
kmartin@planmymortgage.ca
Fax: 1-604-454-0842

RECENT POSTS
By Katherine Martin • September 23, 2026
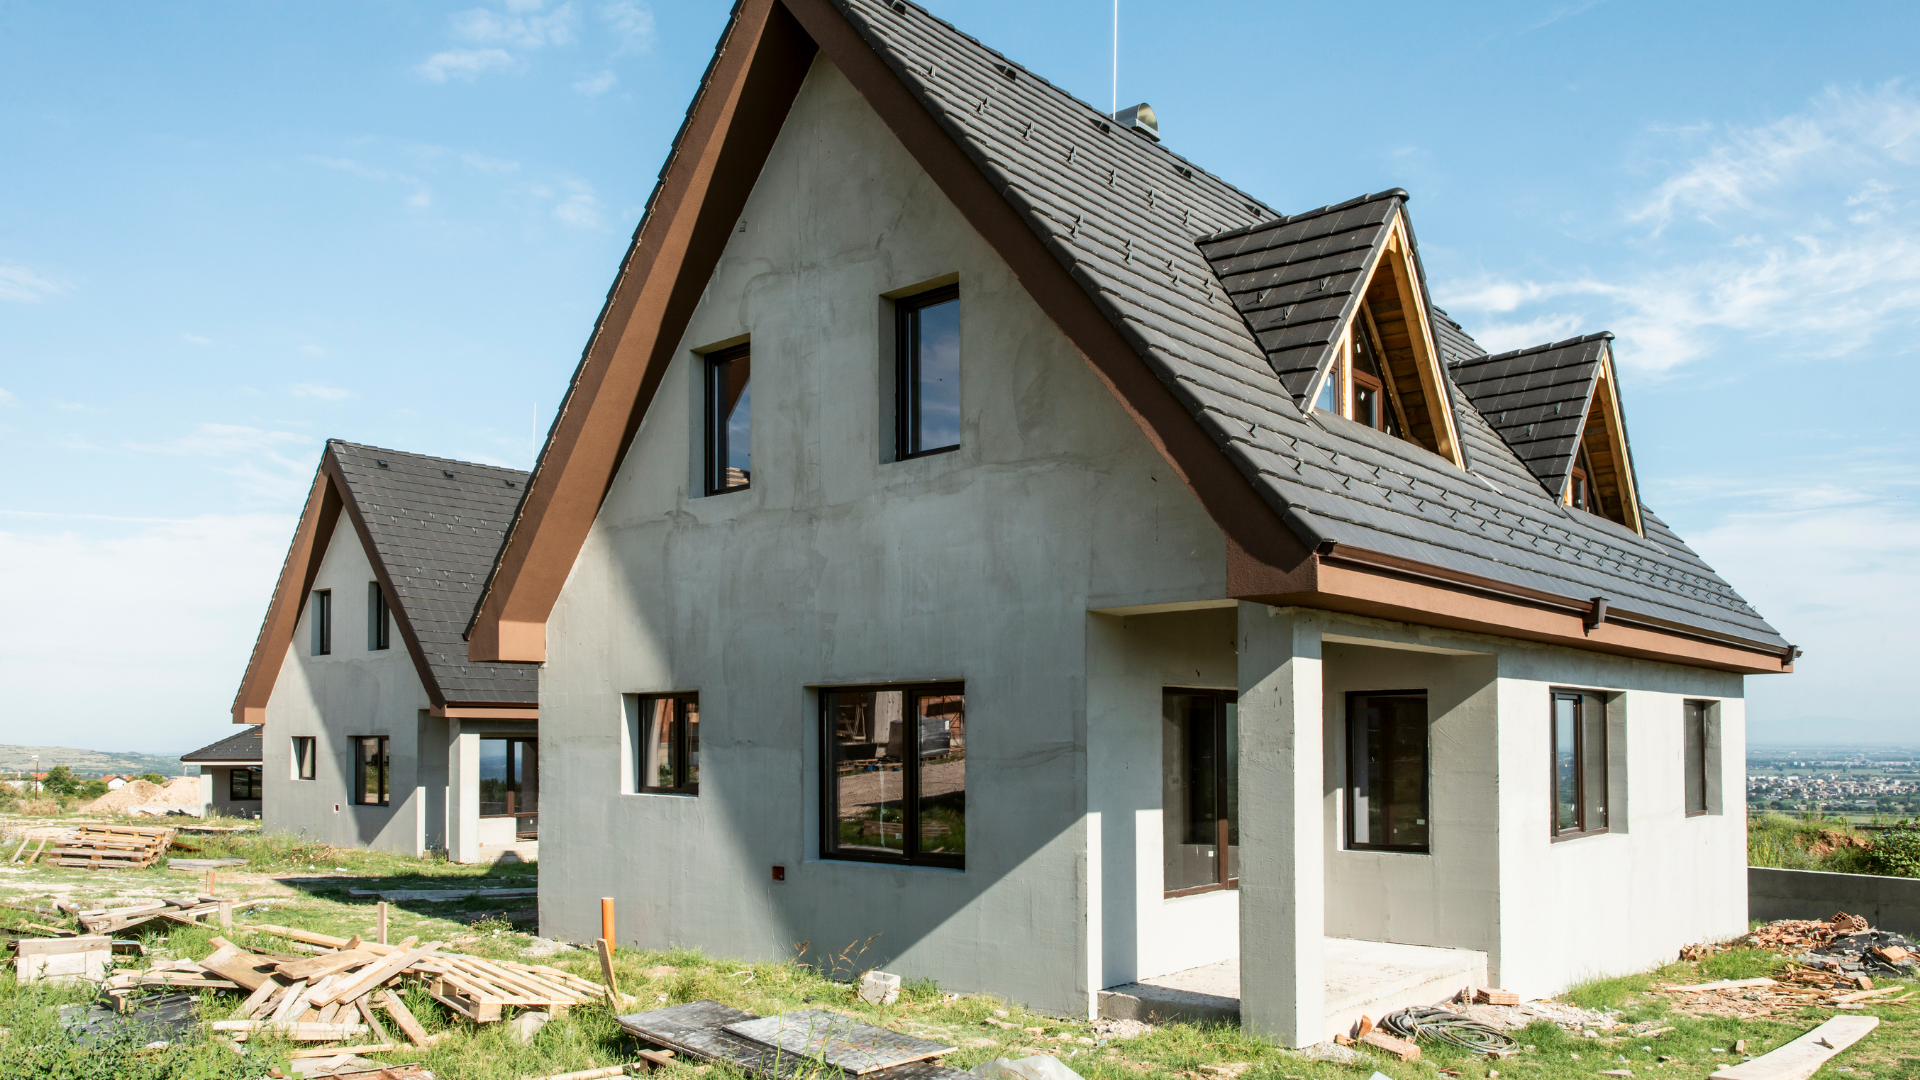
Why More Mortgage Options Matter—Especially for Assignment Purchases One of the biggest advantages of working with an independent mortgage professional is access to choice. Instead of being limited to one lender and one set of products, mortgage brokers work with multiple lenders—each with different guidelines, risk tolerances, and mortgage solutions. That flexibility becomes especially valuable when your situation doesn’t fit neatly into a “standard” box. A great example of this is purchasing new construction through an assignment contract . Why Assignment Purchases Can Be Challenging Assignment purchases are often viewed as higher risk by traditional lenders. Rather than declining these deals outright, many lenders quietly make them difficult by adding layers of conditions, restrictions, or uncertainty. This can lead to delays, frustration, or financing falling apart late in the process. The Good News There are lenders—available exclusively through the broker channel —that have clear, favourable policies for assignment purchases. With the right lender and proper planning, these transactions are absolutely doable. Typical Financing Requirements for Assignment Purchases While every situation is unique, many lenders that allow assignment financing look for the following: Standard purchase qualification, including income verification, credit, and down payment Assignments accepted at either the original purchase price or current market value Minimum 620 credit score , with no prior bankruptcies or consumer proposals The full down payment must come from the purchaser —seller incentives cannot be used Required Documentation To secure financing, lenders typically require: The original purchase agreement signed by all parties The MLS listing (if applicable) The assignment agreement signed by the builder, original purchaser, and new buyer Any side agreements outlining changes to the purchase price A full appraisal to confirm value This list isn’t exhaustive, but it highlights that while assignment purchases require more coordination, they are very achievable with the right lender and guidance. Final Thoughts Assignment contracts can open doors to great opportunities—but only if your financing supports the transaction. This is where access to multiple lenders and specialized policies makes a real difference. If you’re considering purchasing new construction through an assignment, or if you’d like to explore more traditional purchase options, feel free to connect anytime. I’d be happy to walk you through the mortgage products available and help you choose an option that doesn’t limit your financing possibilities.
By Katherine Martin • September 16, 2026
How Mortgage Payment Frequency Affects What You Pay Over Time You’ve probably heard the saying that there are two certainties in life: death and taxes. When it comes to your mortgage, there’s really just one certainty—you’ll repay what you borrow, plus interest. What is flexible, though, is how often you make your mortgage payments. And that choice can have a meaningful impact on how quickly you pay down your mortgage and how much interest you pay over time. The Six Mortgage Payment Frequencies Most lenders offer the following payment options: Monthly – 12 payments per year Semi-monthly – 24 payments per year Bi-weekly – 26 payments per year Weekly – 52 payments per year Accelerated bi-weekly – 26 payments per year Accelerated weekly – 52 payments per year Standard Payment Frequencies The first four options are designed to align with how you get paid. For example: Paid monthly? Monthly mortgage payments may make sense. Paid every two weeks? Bi-weekly payments can align nicely with your cash flow. With these standard options, regardless of how often you pay, the total amount paid over the year is the same —it’s simply divided into more frequent payments. What Makes “Accelerated” Payments Different Accelerated payments work differently—and this is where the real savings happen. With accelerated bi-weekly or accelerated weekly payments, you’re paying a slightly higher amount each time. That extra money goes directly toward reducing your mortgage principal, which lowers the interest you’ll pay over the life of the mortgage. A Simple Example Let’s assume a $1,000 monthly mortgage payment: Monthly: $1,000 once per month = $12,000 per year Semi-monthly: $500 twice per month = $12,000 per year Bi-weekly: $1,000 × 12 ÷ 26 = $461.54 every two weeks = $12,000 per year Accelerated bi-weekly: $1,000 ÷ 2 = $500 every two weeks = $13,000 per year With accelerated bi-weekly payments, you effectively make two extra payments per year without having to think about it. Those extra payments reduce your principal faster, which lowers interest costs over time. Accelerated weekly payments work the same way—you just make smaller payments more frequently. Why This Matters Long Term While it’s difficult to calculate exact savings due to variables like interest rates, terms, and amortization changes, maintaining an accelerated payment schedule over the life of your mortgage can reduce your amortization by up to three years and save a significant amount of interest. The Bottom Line Accelerated payments are a simple, automatic way to lower your overall cost of borrowing—without needing to make lump-sum payments or drastically change your budget. If you’d like to see how different payment frequencies would impact your mortgage specifically, feel free to reach out anytime. I’d be happy to walk through the numbers with you and help you choose the option that fits your goals.